Short-stay and mid-term management in Pyrmont
Pyrmont added 18.1% more short-stay listings over the twelve months to September 2026 and its occupancy went up anyway — 4.6 points, the strongest demand growth of any suburb covered on this site. Every other inner-city market here absorbed new supply by giving up rate or occupancy. Pyrmont did not, and the convention centre is most of the reason.
How we read this market
MetaWise has priced short-stay calendars through Sydney's event and convention weeks since 2009, which is the part of Pyrmont's year that decides the rest of it. The figures on this page come from the PriceLabs short-term rental index for the Pyrmont official boundary — 228 active listings, twelve months to September 2026 — each traceable to that source. They are the market's, and our owners' own figures are not published.
Demand
What actually fills a calendar here
The ICC and a calendar set by conferences
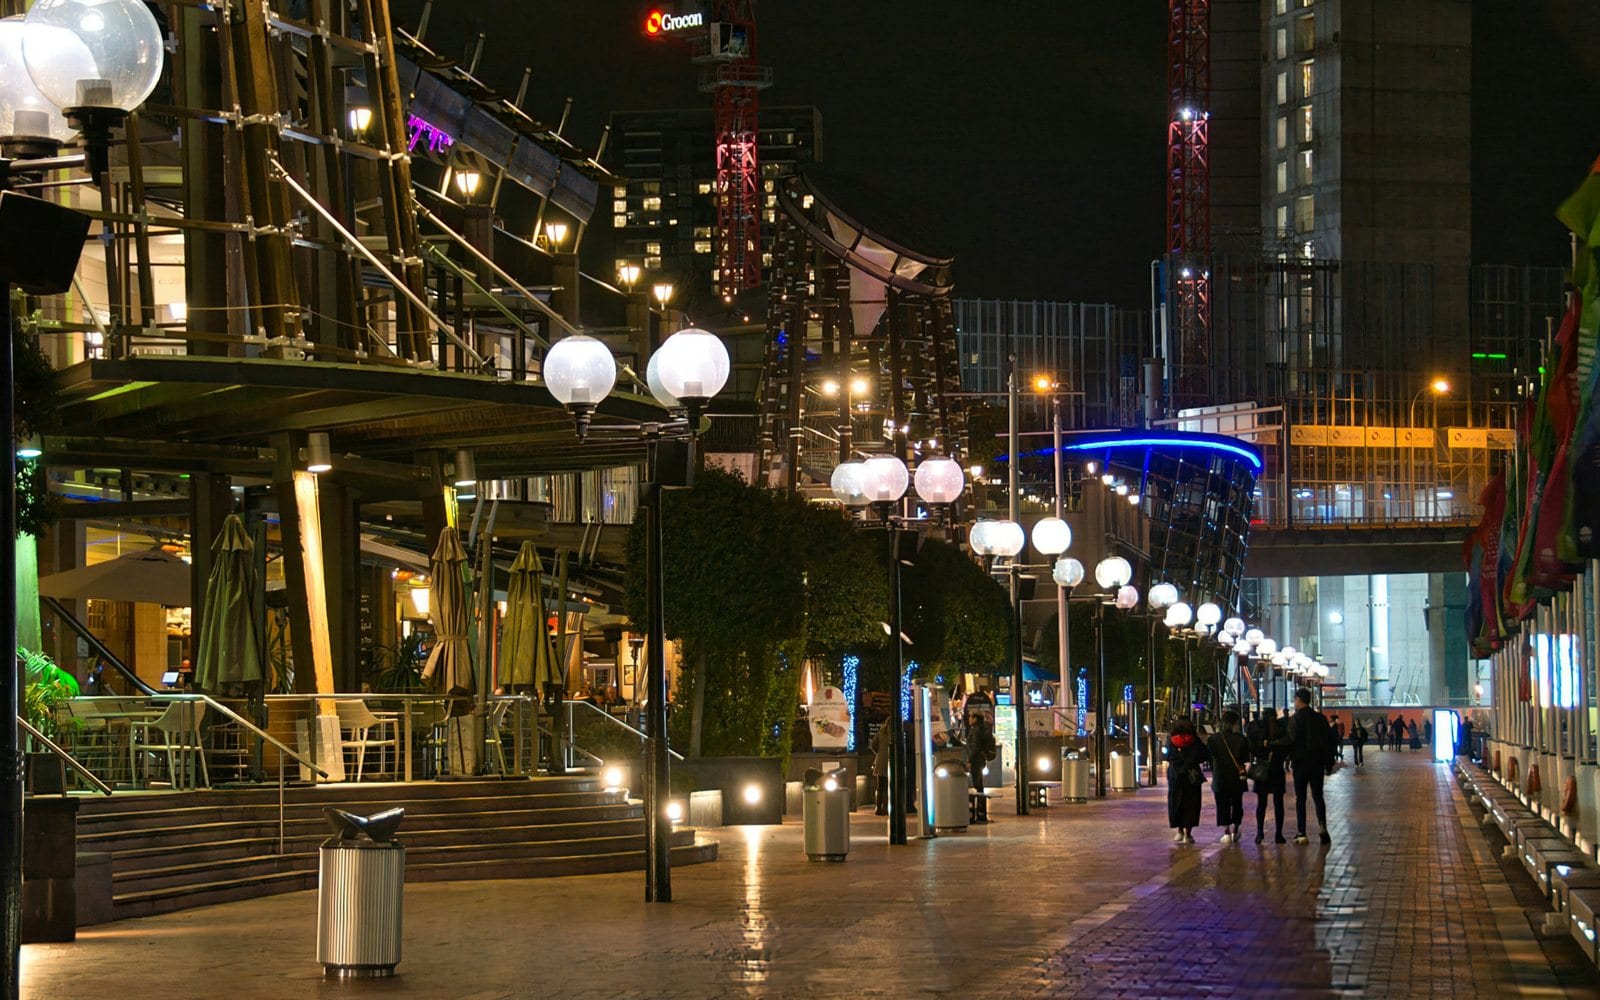
Sydney's convention centre is a few minutes' walk away, and a major conference fills every bed within walking distance regardless of season. That is demand that does not care about weather, school holidays or the exchange rate, and it is why February occupancy here rose 11.6 points year-on-year.
Darling Harbour on foot, the CBD across a bridge
Guests get the harbour, the restaurants and the aquarium without paying a CBD rate, and the city itself is a ten-minute walk over Pyrmont Bridge. It is one of the few places in Sydney where a guest can genuinely do without transport for an entire stay.
An employment base that books its own rooms
The technology and media offices around Pyrmont and Ultimo generate their own steady midweek demand — contractors, project teams, visiting staff — which fills the weeks between conferences and keeps the calendar from depending on any single driver.
Property types
What works here
- Apartments in the harbourside towers within a walk of the ICC and Darling Harbour
- Converted warehouse and wharf apartments on the Pyrmont Point side
- One and two-bedroom apartments suited to conference and project-team stays
Operations
What makes it hard
- Demand here is event-shaped. Conference dates are published well in advance, and a calendar that is not priced against them leaves the most reliably forecastable money in Sydney on the table.
- Supply is growing fast — 193 listings to 228 in a year. Pyrmont has absorbed it so far, but the Surry Hills pattern of rate erosion is the thing to watch.
- Harbourside towers mean building access, loading docks and concierge procedures. Turnover logistics are a scheduling problem here rather than a physical one.
Rules
Compliance in this area
General information about how the NSW framework applies here, not advice on your building.
- Pyrmont is in the City of Sydney and inside Greater Sydney, so the 180-night non-hosted cap and STRA registration both apply.
- Conference-driven demand concentrates into identifiable weeks, which makes Pyrmont one of the easier suburbs in which to plan the 180 nights deliberately rather than spend them first-come-first-served.
- Tower strata schemes here are generally newer and their short-term letting positions are more consistently documented than in the older suburbs, but the by-law still decides the question.
Coverage
Suburbs we service from here
Pyrmont · Ultimo · Darling Harbour surrounds · Glebe border · Sydney Fish Market surrounds
Questions
Pyrmont — the only market here where demand outgrew new supply — frequently asked
What makes Pyrmont different from the other inner-city suburbs?
It is the only one covered here where demand growth clearly beat new supply. Listings rose 18.1% over the year and occupancy still gained 4.6 points, positive in ten of twelve months. In Surry Hills the same scale of new supply pushed the average rate down instead.
How much does the convention centre really drive?
Enough to show up plainly in the numbers. February occupancy was 11.6 points above the previous February and October 2025 was 10.6 points above its prior year — both months heavy with conference activity. Annual revenue per listing came to roughly A$91,256, second only to Kirribilli among the suburbs here.
Is the growth in listings a warning sign?
It is the thing to monitor. Pyrmont has absorbed the new supply without the rate damage Surry Hills took, but 18.1% growth in a year is substantial. The honest position is that the market is currently strong enough to carry it, and that this is a condition to re-check rather than assume.