Where MetaWise manages property
We take on properties across Australia. We publish an area page only where we manage property and have something specific to say about it — not a page for every suburb we work in. An area without a page here is not an area we decline; it is one we have not earned the right to write about yet.
Sydney is the home market and where the portfolio is deepest, so Sydney is what these pages cover.
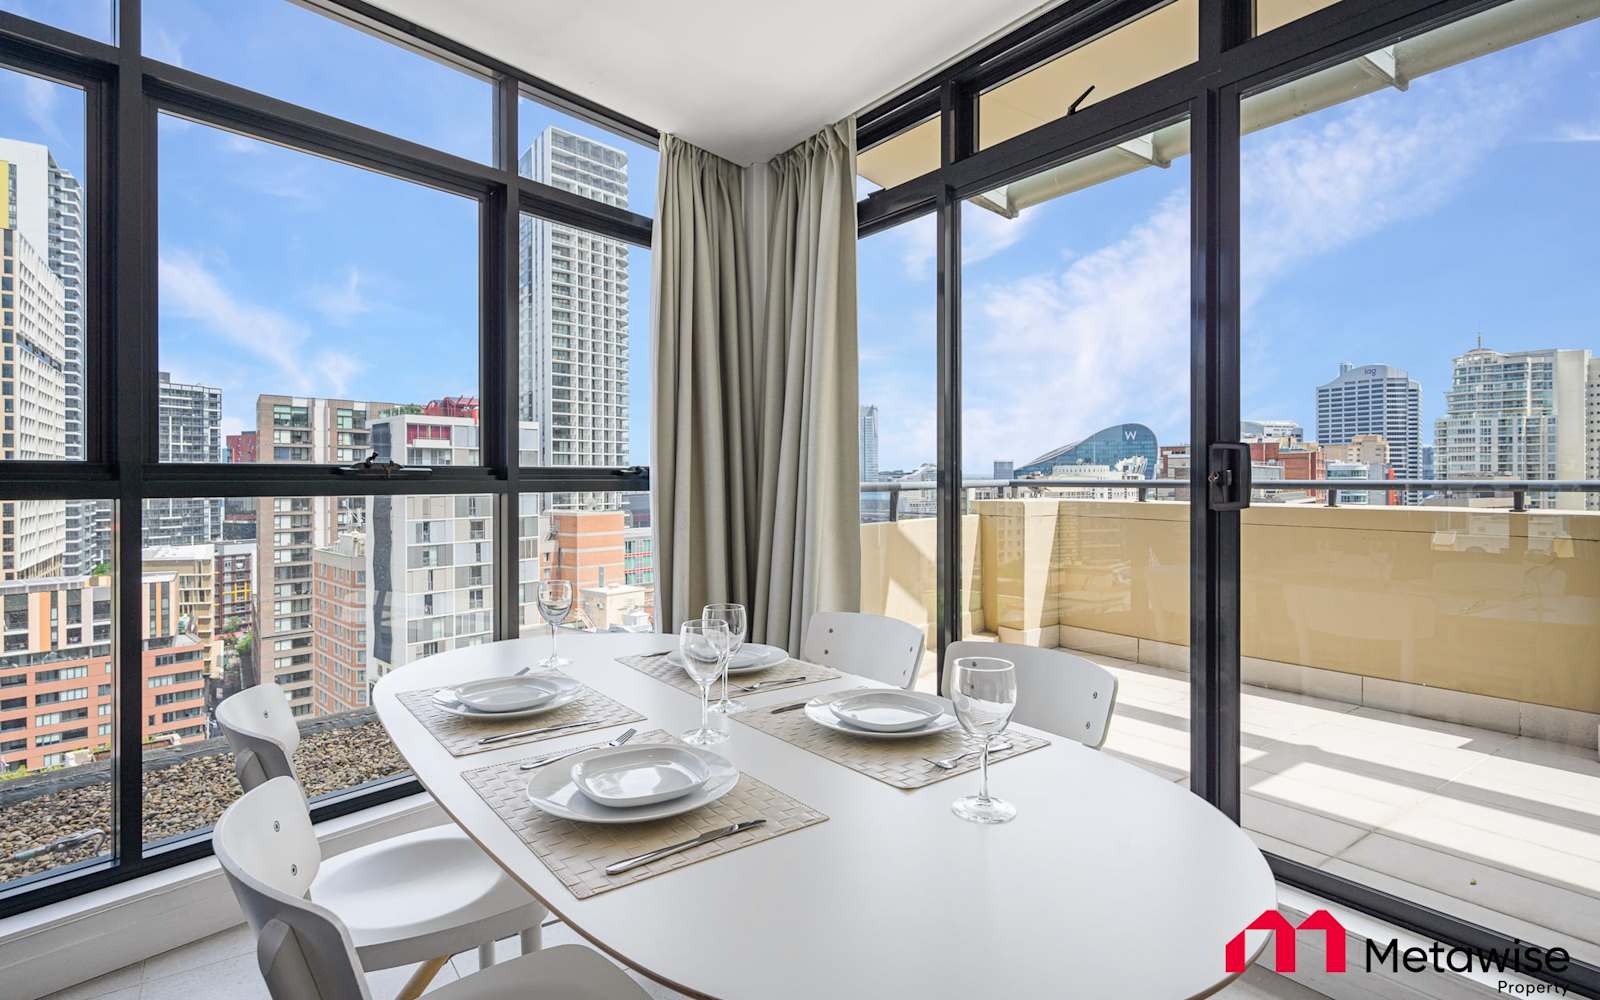
Sydney CBD, Haymarket & Darling Harbour
The largest part of our portfolio is here. In the CBD, operational detail decides the return more than the listing photograph does: lifts, loading docks, building access and the city event calendar.
Sydney CBD · Haymarket and Chinatown · Darling Harbour · Pyrmont · Millers Point and The Rocks · Town Hall and the Hyde Park surrounds
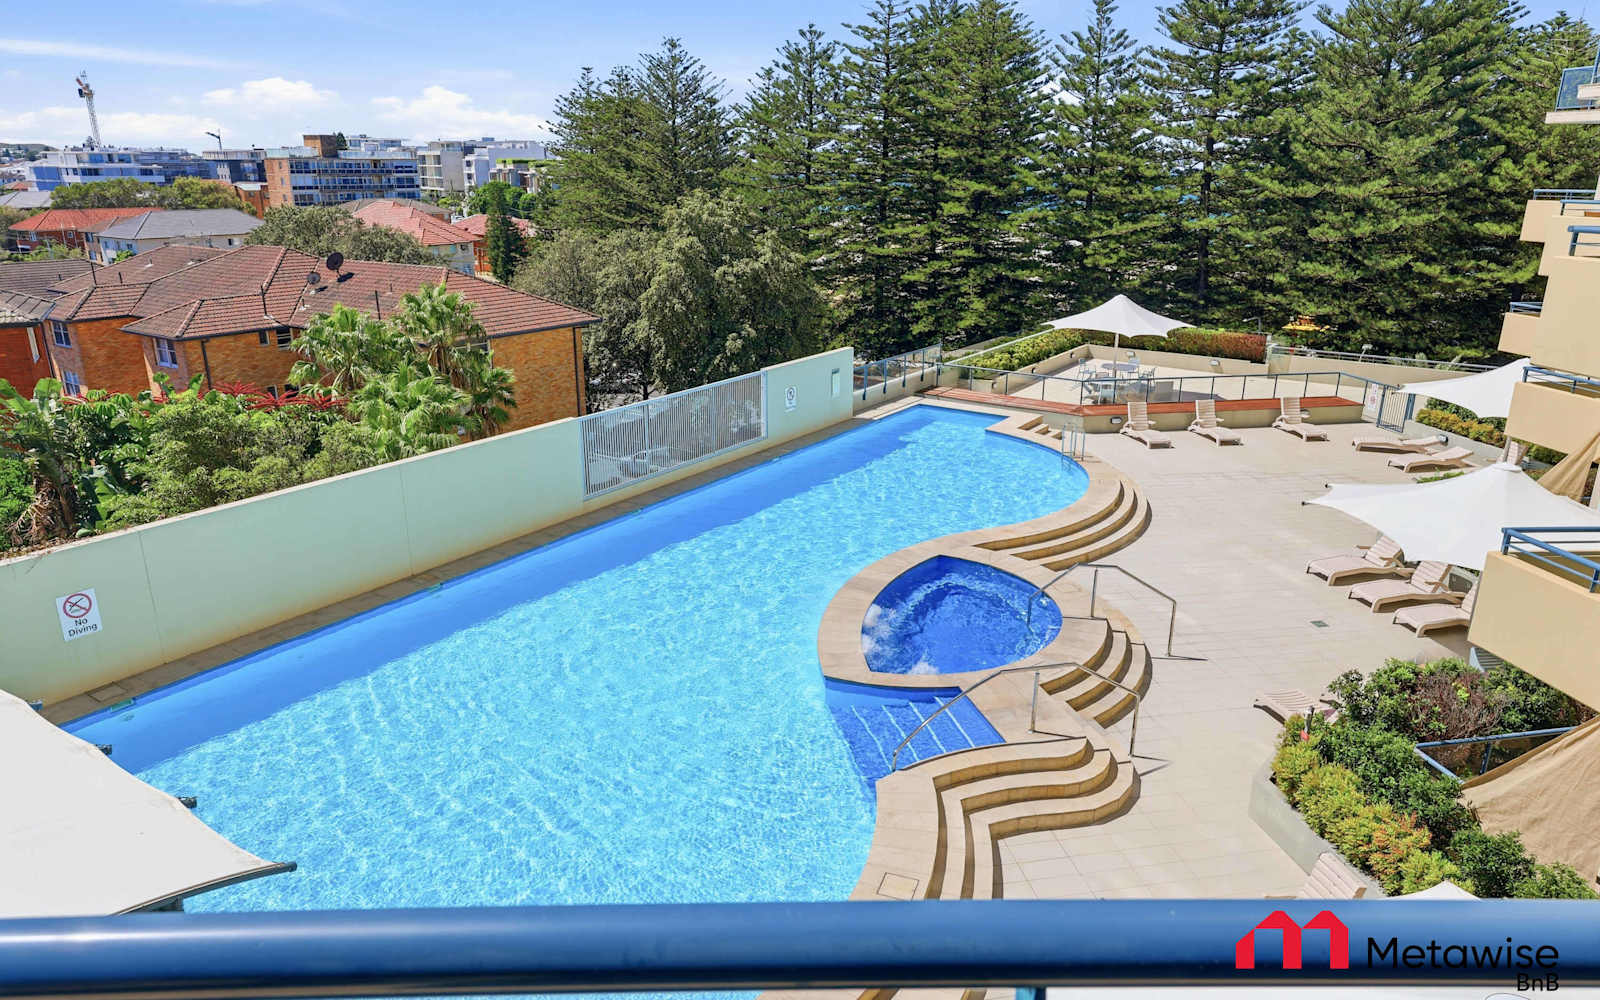
Cronulla & the Sutherland Shire
Cronulla is the most seasonal market we operate in. That makes disciplined pricing and a second source of demand more important here than anywhere else.
Cronulla · Woolooware · Caringbah · Miranda · The Sutherland Shire generally
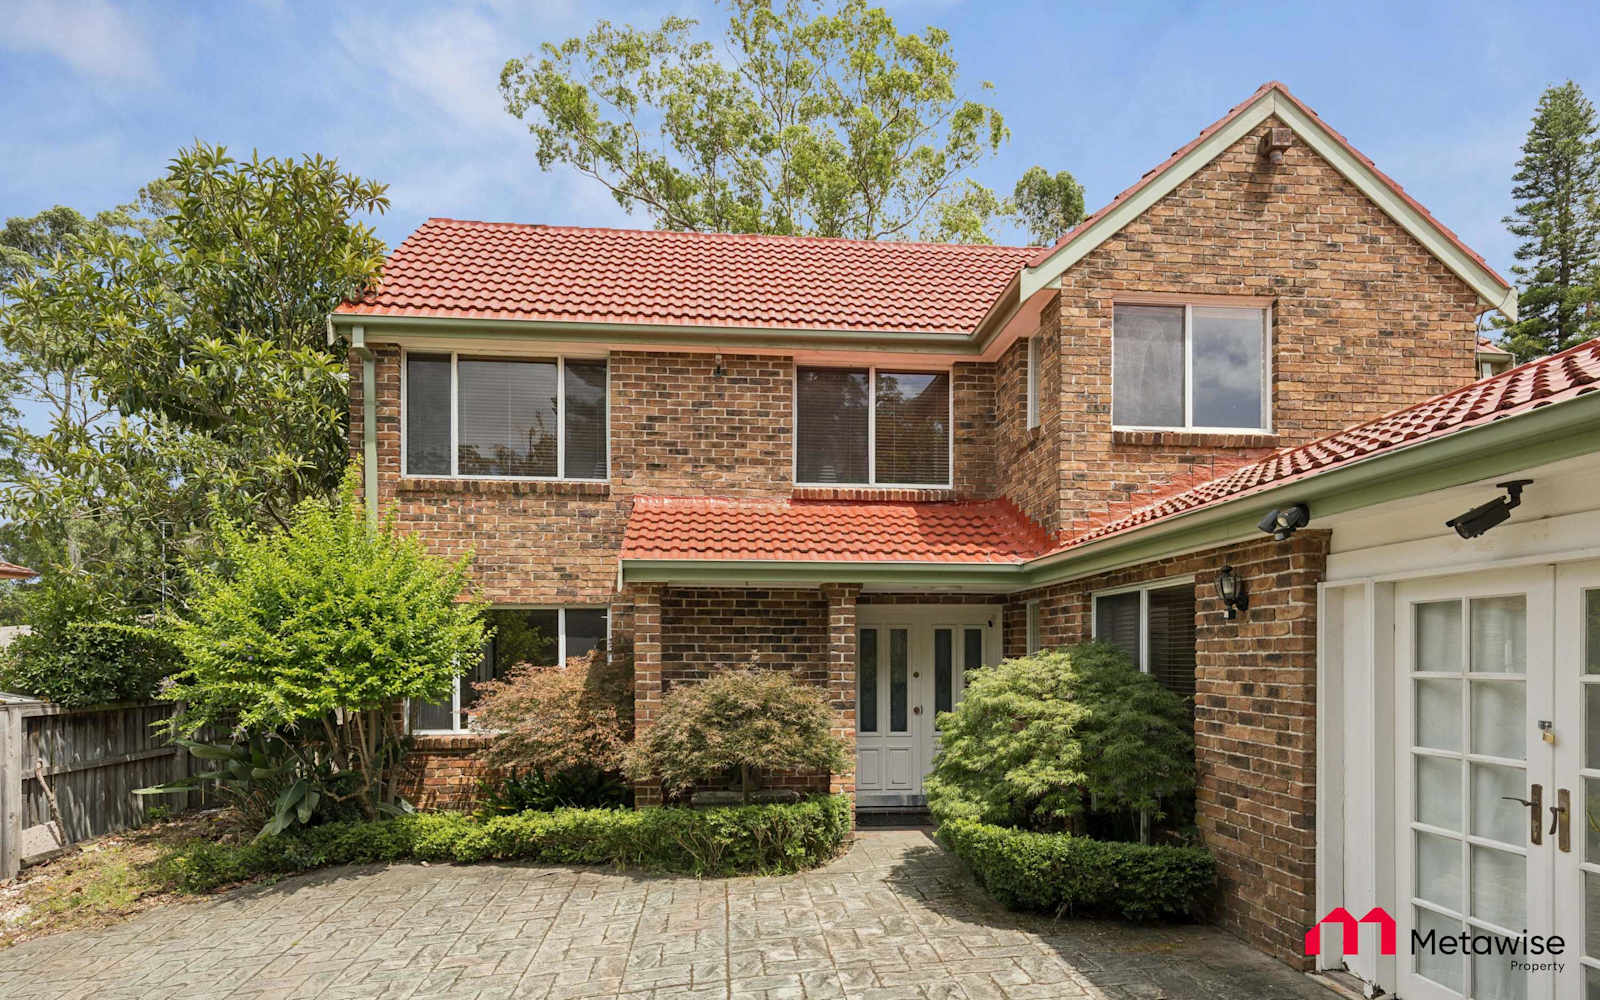
Castle Hill & the Hills District
The Hills is not a tourist market and should not be run as one. Its guests are families, relocations and project workers, and properties set up for them earn more than properties styled for a weekend away.
Castle Hill · Cherrybrook · Baulkham Hills · Kellyville · Rouse Hill and Tallawong
Inner West — Camperdown, Petersham & Earlwood
The Inner West is not a tourist market and does not need to be. Its demand comes from two hospitals, a university, and the people who need to stay near them for weeks at a time. That makes it the best part of Sydney for a mid-term strategy.
Camperdown · Newtown surrounds · Petersham · Stanmore · Marrickville · Earlwood
Eastern Suburbs — Bondi Junction, Darlinghurst & Rushcutters Bay
Guests pay for location here all year round: the beach, the harbour and the city are all close. The hard work is in the buildings. Which ones permit short-term letting, which have the lift and parking that make a turnover easy, and which will resist you.
Bondi Junction · Darlinghurst · Rushcutters Bay · Elizabeth Bay · Potts Point · Paddington surrounds
Northern Beaches — Seaforth, Balgowlah & Manly surrounds
The Northern Beaches is a house market rather than an apartment market, and many of those houses belong to owners who are away for months at a time. Managed well, a home that sits empty half the year can pay for itself.
Seaforth · Balgowlah · Clontarf · Manly surrounds · Fairlight · The Spit
Randwick — the hospital, the university and the racecourse
Randwick is the rare Sydney market where the nightly rate is climbing rather than being competed down. In the twelve months to September 2026 the average rate rose 15.6% and occupancy rose 4.1 points with it. That combination is unusual, and it is not tourism doing it. It is a hospital, a university and a racecourse filling different weeks of the same year.
Randwick · Kingsford · Kensington · Coogee surrounds · Clovelly surrounds
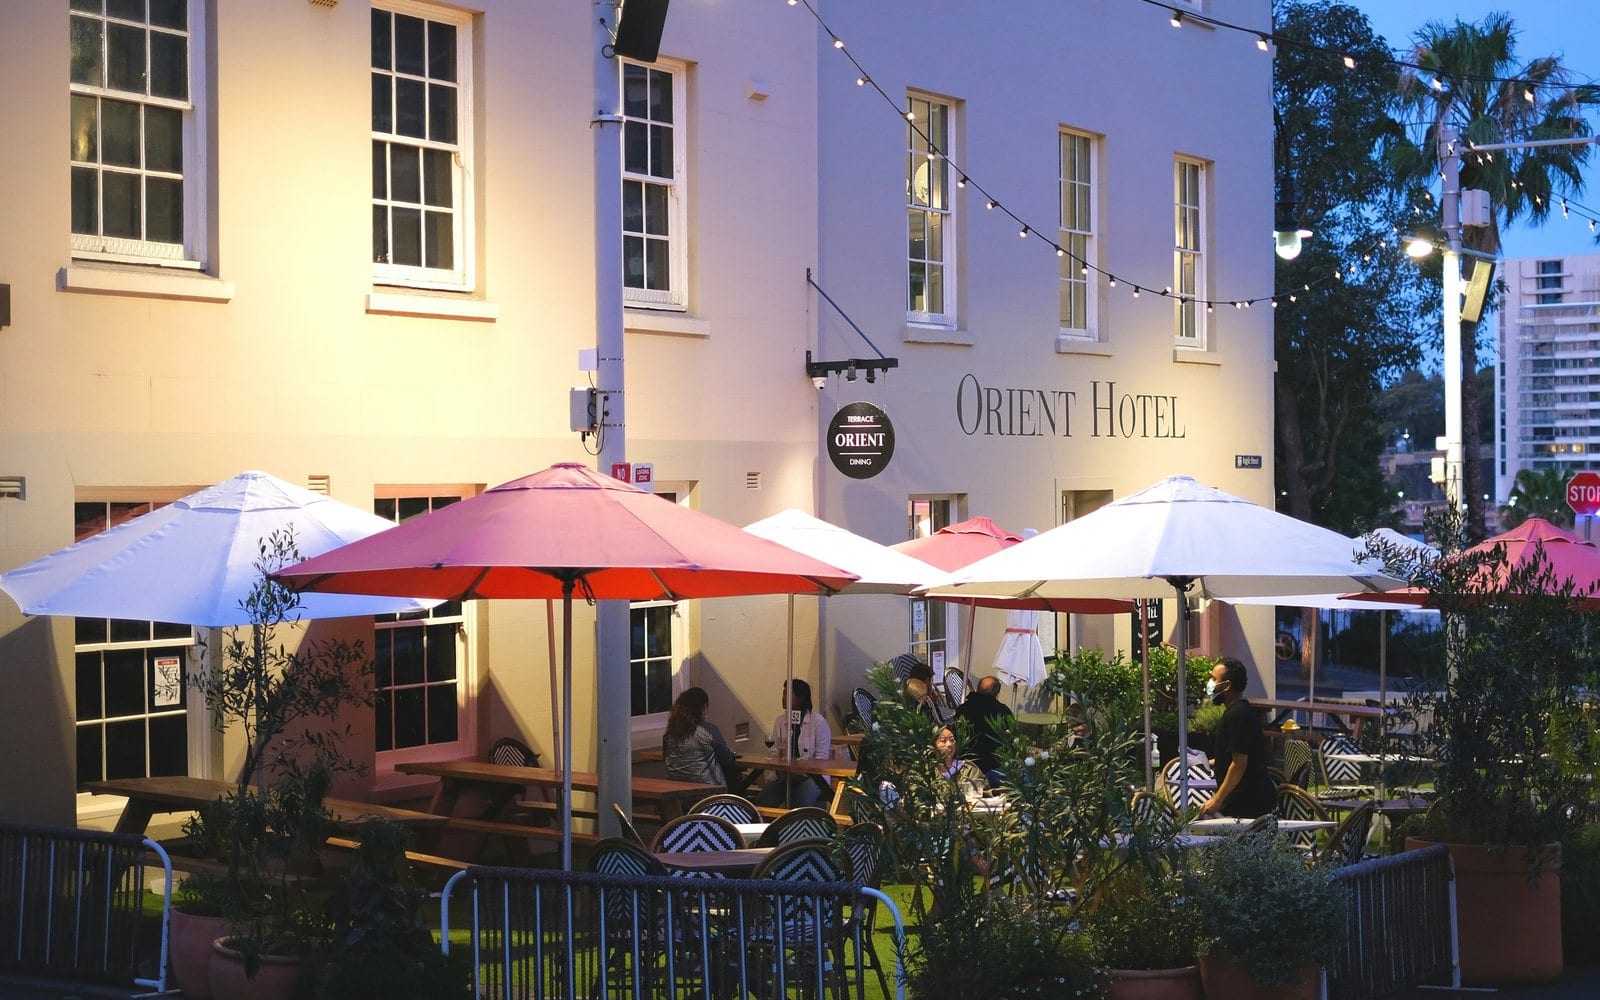
Surry Hills — the most crowded short-stay market in the inner city
Surry Hills has 624 active short-stay listings, more than twice any other suburb on this side of the city, and it added nearly a hundred of them in twelve months. That is the single most important fact about operating here. Supply grew 18.9% in a year, and the market's response was to trade rate for occupancy rather than hold the line.
Surry Hills · Redfern surrounds · Chippendale · Moore Park surrounds · Strawberry Hills
Potts Point — the one inner-city market where rates are still rising
Of the inner-city suburbs on this site, Potts Point is the only one where the nightly rate went up over the twelve months to September 2026 — up 5.0%, and positive in eleven of twelve months. The explanation is not a demand story. It is that supply barely moved while everywhere around it was adding listings.
Potts Point · Elizabeth Bay · Rushcutters Bay · Woolloomooloo · Kings Cross
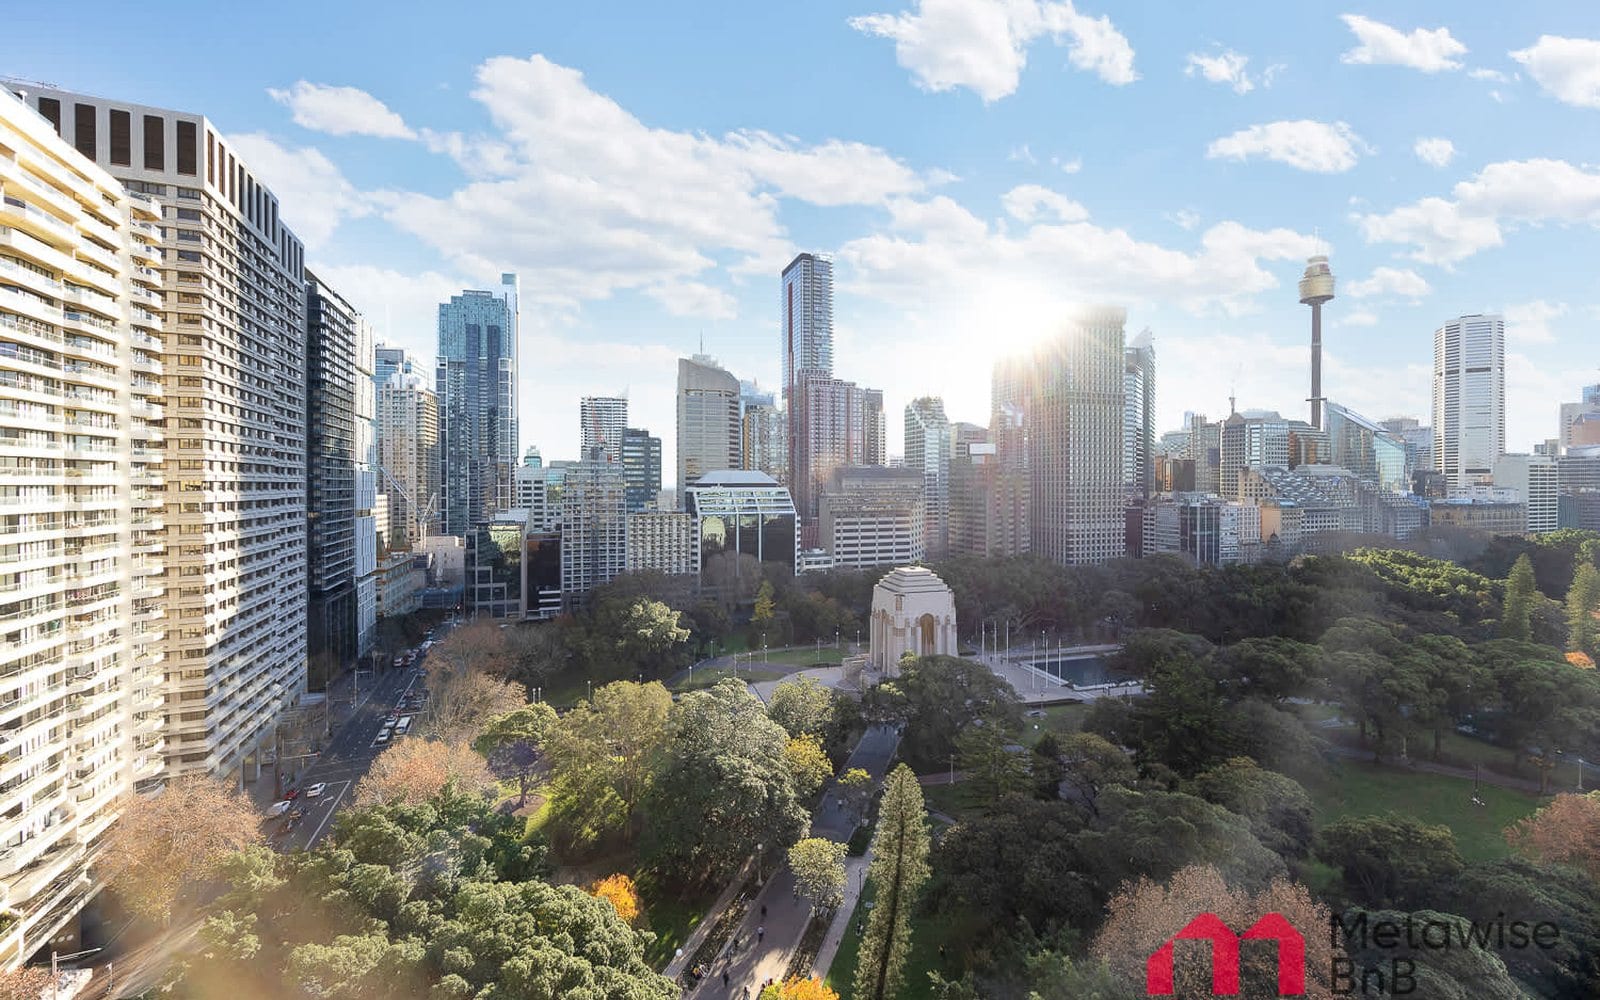
Darlinghurst — the highest occupancy in the inner city, and what it cost
Darlinghurst is the only suburb covered on this site that averaged above 80% occupancy for the year, and it held 80% or better for six consecutive months. It also cut its nightly rate in nine months out of twelve to do it. A full calendar and a falling rate are the same decision seen from two sides, and it is worth knowing which one a property is being managed for.
Darlinghurst · Surry Hills border · Paddington surrounds · Woolloomooloo · East Sydney
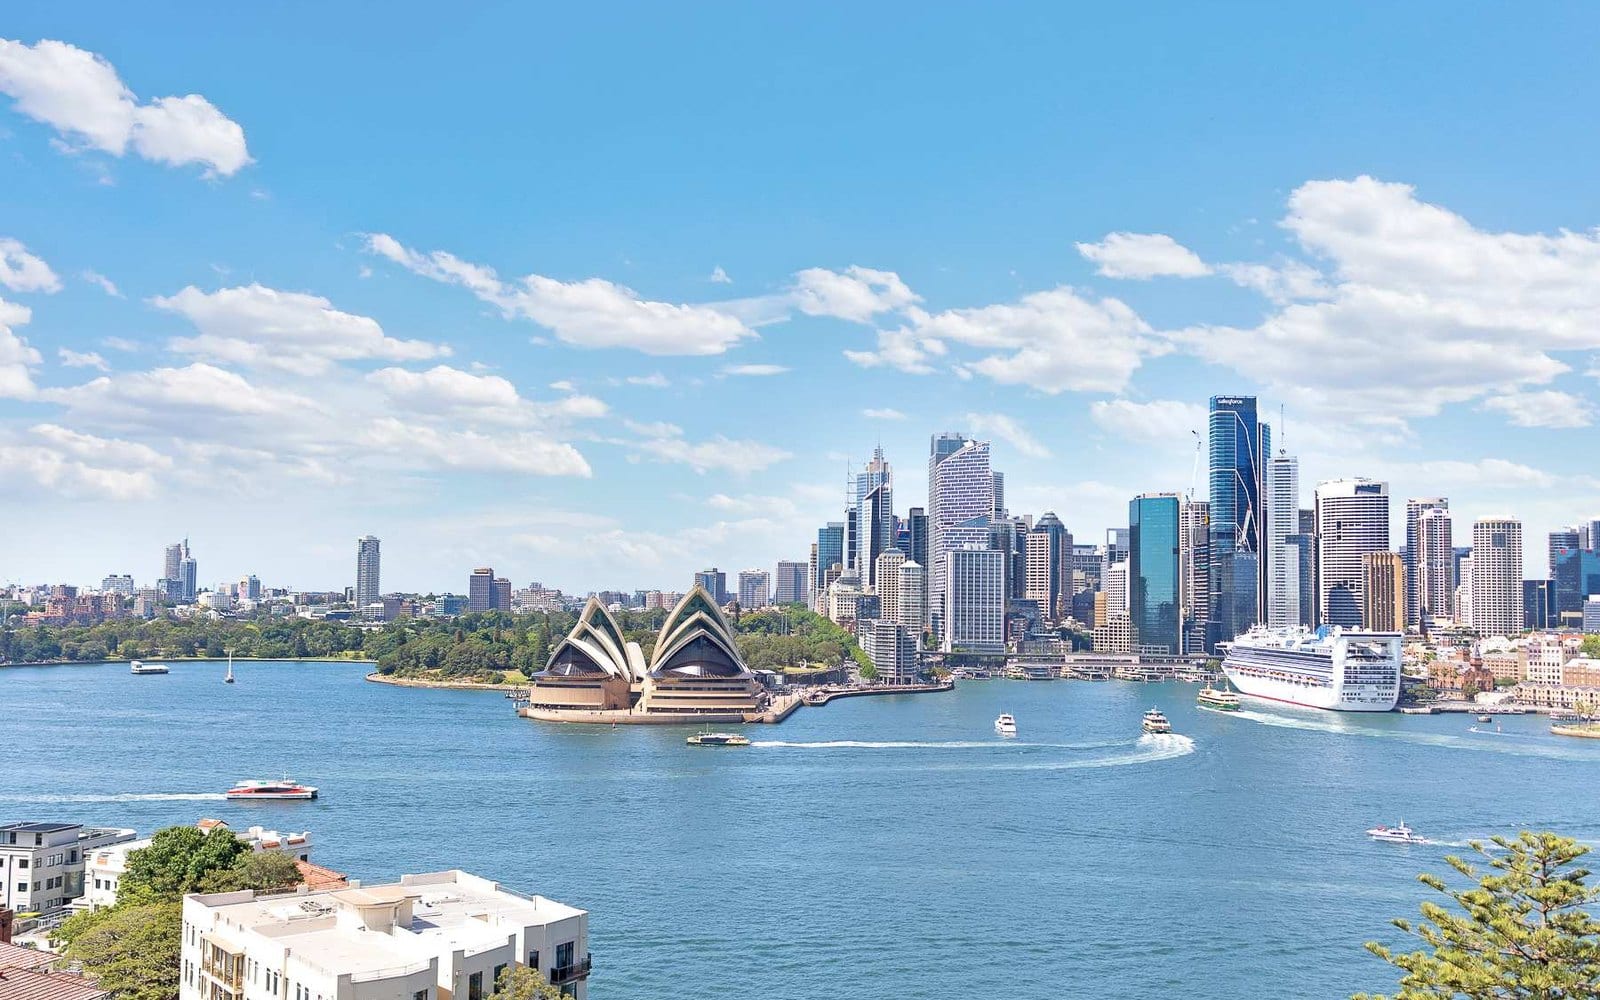
Kirribilli — the smallest supply and the highest rate on the harbour
Kirribilli has 123 active short-stay listings — the smallest supply base of any suburb covered here — and the highest average nightly rate, at A$476.62. That is 68% above Surry Hills, which has five times as many listings. Scarcity on a harbour frontage is the whole economic story of this suburb, and December is where it becomes obvious.
Kirribilli · Milsons Point · Lavender Bay · McMahons Point · North Sydney surrounds
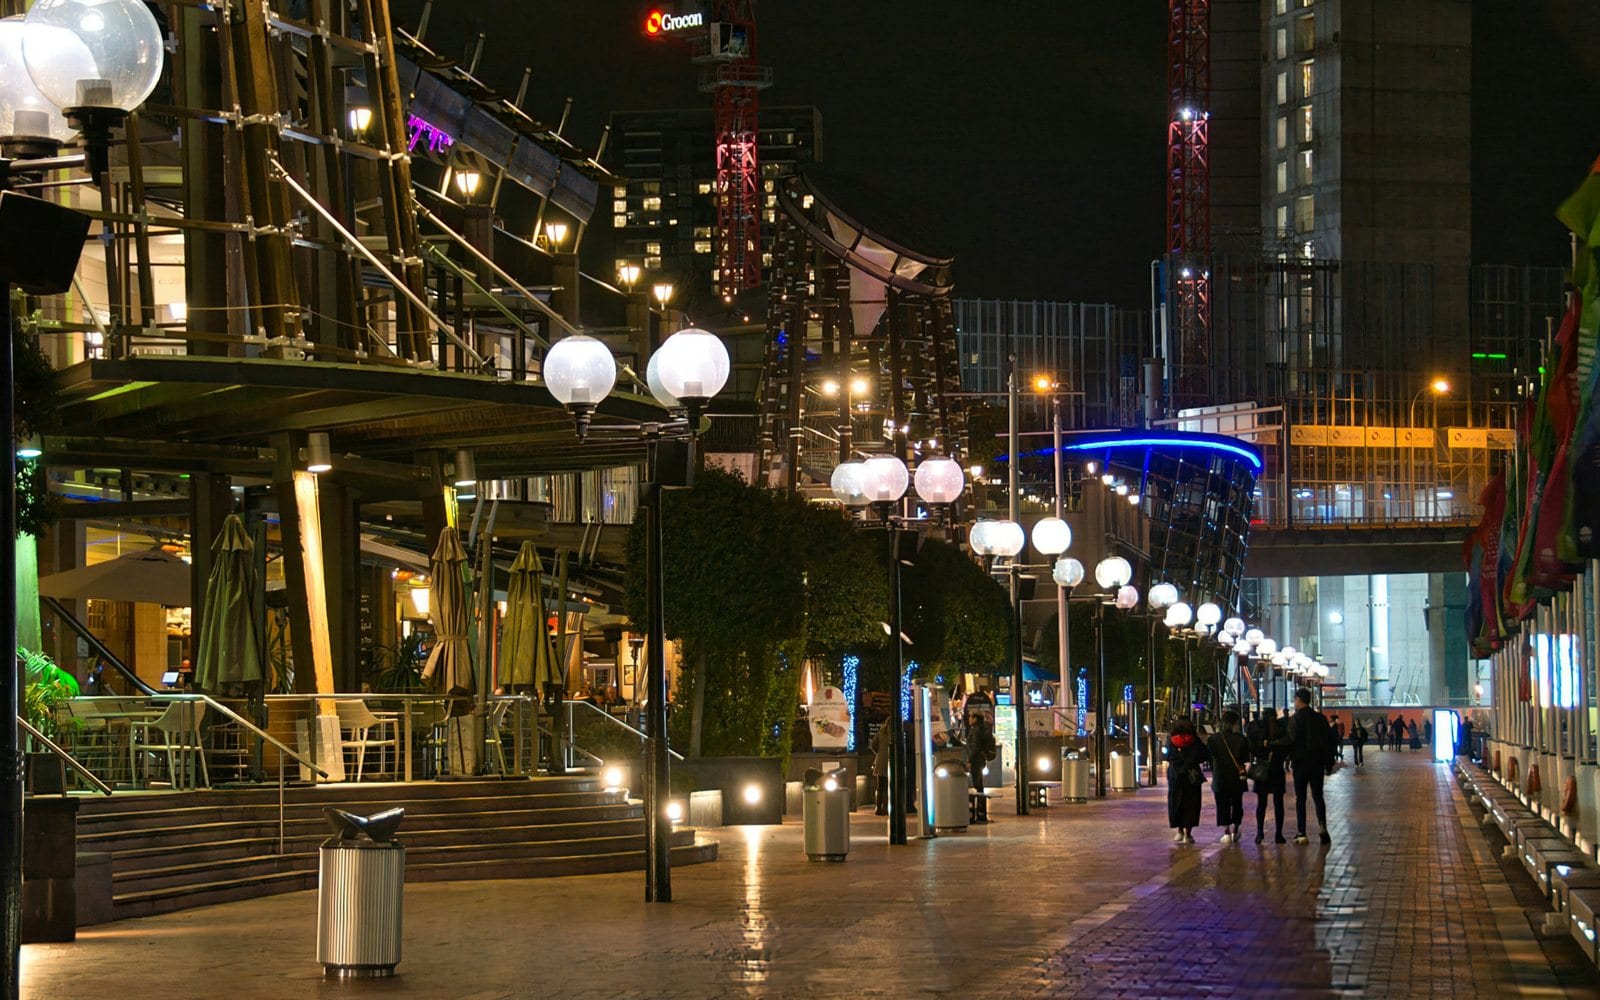
Pyrmont — the only market here where demand outgrew new supply
Pyrmont added 18.1% more short-stay listings over the twelve months to September 2026 and its occupancy went up anyway — 4.6 points, the strongest demand growth of any suburb covered on this site. Every other inner-city market here absorbed new supply by giving up rate or occupancy. Pyrmont did not, and the convention centre is most of the reason.
Pyrmont · Ultimo · Darling Harbour surrounds · Glebe border · Sydney Fish Market surrounds
Not on the list?
We take on properties across Australia, not just in the suburbs listed above. Ask us about yours. If we know the area, we will tell you what we know. If we do not, we will say so and tell you what we would need to look at before quoting.